
Adani Power Shares: Capacity, Electricity Sales, Costs and Cash Flow
Understand Adani Power shares through capacity, generation, electricity sales, fuel costs and cash collection, with clear fictional calculation examples.
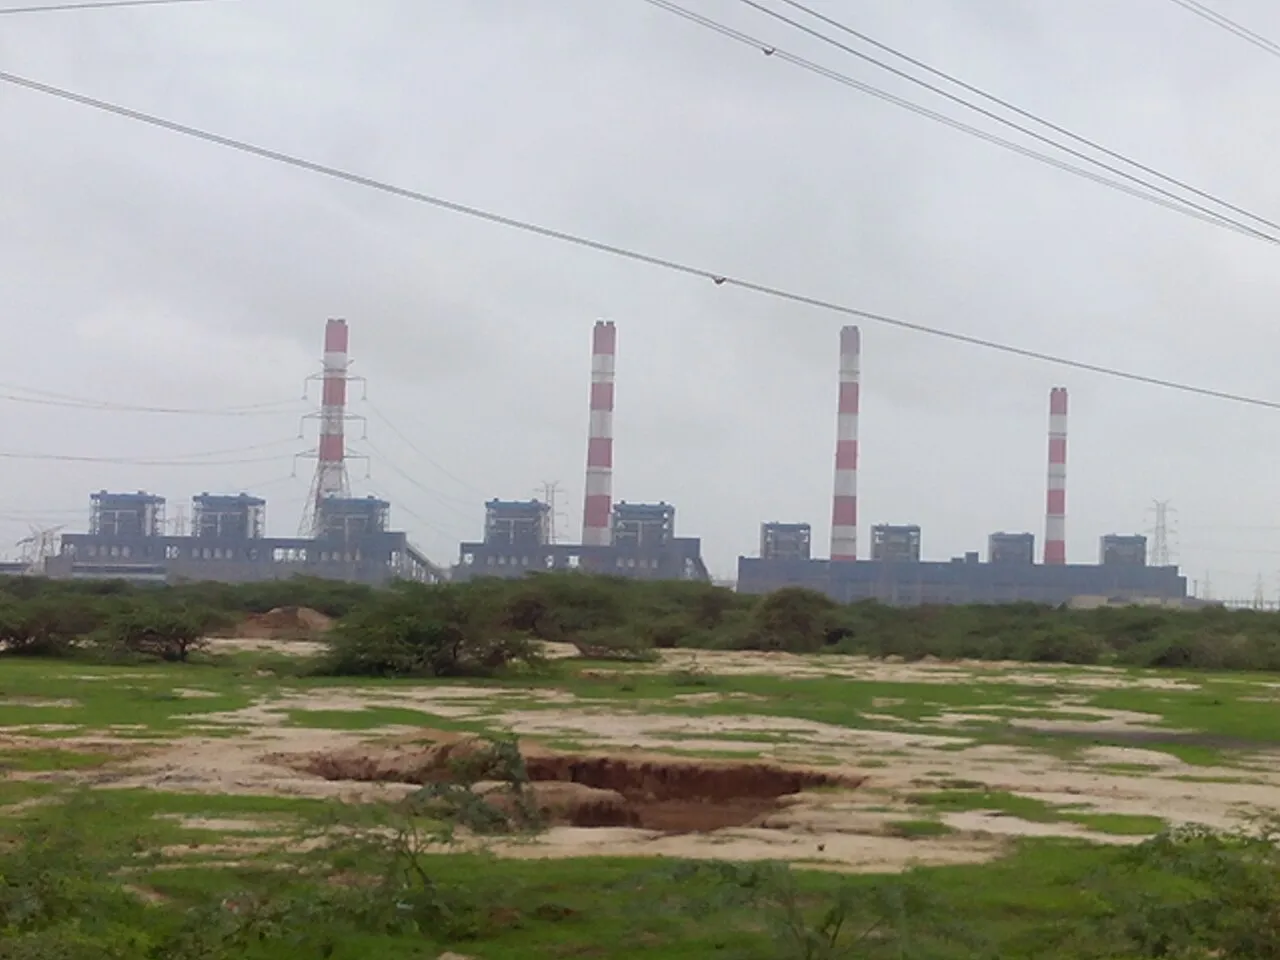
Adani Power share-price searches should begin with Adani Power Limited, the electricity-generation company, rather than another listed Adani business. The group's companies are not interchangeable securities. A current quote requires the correct exchange, security and timestamp; an undated screenshot cannot establish today's market price.
The official group overview describes a predominantly thermal-generation business, while the exchange filing identifies the listed entity and reporting scope. This guide explains generation capacity, electricity output, plant utilisation, contracts, fuel costs and financial results. It uses clearly fictional calculations for learning and does not offer a target price or a recommendation to trade.
Identify the power company before reading a chart
Different companies in a business group can operate in generation, transmission, distribution or other activities. Those roles have different assets and financial measures. A shared group name is not enough reason to use one company's earnings to explain another company's share chart.
The October 2026 exchange filing identifies Adani Power Limited and the symbol ADANIPOWER. Keep that identity beside the period, currency and reporting scope when extracting data. It prevents a correct number from becoming misleading through association with the wrong company.
| Measure | What it describes |
|---|---|
| Installed capacity | Rated generating capability |
| Electricity generated | Energy produced over time |
| Electricity sold | Relevant reported sales quantity |
| Revenue | Recognised financial income from activities |
| Cash collected | Actual receipts under the cash-flow record |
Megawatts and electricity units are not interchangeable
Capacity describes a rate of potential production under stated conditions. Energy describes production over time. A megawatt is a power unit; a megawatt-hour is an energy unit. Confusing them can make a capacity announcement sound like completed electricity generation.
For a fictional generator running at a constant 100 megawatts for ten hours, energy output is 1,000 megawatt-hours under the simplified assumptions. If it runs for five hours instead, output is 500. The installed rating alone does not establish which total occurred.
Actual generation depends on availability, dispatch and operating conditions. Use the company's reported output for its actual performance. A photograph of a large plant proves neither the amount produced during a period nor the price at which the electricity was sold.
Capacity additions need operational dates
An announced project, construction activity, a completed unit and a unit contributing to financial results represent different stages. A capacity figure should say whether it is operational, being commissioned, acquired or planned. The distinction matters when comparing two reporting dates.
Imagine a fictional company that operates 1,000 megawatts and announces another 500. Its operating capacity does not instantly become 1,500 merely because a plan has been announced. Construction and commissioning milestones provide later evidence about what is actually available.
For a real expansion, record the stated stage and the date of the disclosure. Do not attach a full year's assumed revenue to a unit that became operational only near the end of the period. The timing can materially change an otherwise simple comparison.
Plant load factor is a utilisation measure
A utilisation measure relates actual production to a defined level of potential production. Its precise calculation should follow the relevant disclosure. It is useful for understanding how an asset operated, but it is not the same as a profit margin or an investment return.
In a fictional example, a unit capable of producing 1,000 energy units over a period produces 700. Its simple utilisation under those assumptions is 70 percent. If the potential or available period changes, the denominator must change as well.
A higher utilisation figure does not independently prove higher profit. Electricity prices, fuel costs, operating expenses and contractual conditions also matter. The measure answers an operating question, and a careful explanation leaves the remaining financial questions visible.
Availability and dispatch answer different questions
A generator can be technically available without being dispatched at its full possible output throughout a period. Available capability and actual electricity production are therefore different ideas. Reports may present different measures to describe them, and each needs its definition.
Think of a fictional machine ready to work for ten hours but used for six. Readiness and use differ without either statement being contradictory. The analogy explains why an available power unit need not have generated at its maximum possible rate continuously.
For company analysis, avoid inventing the cause of a change. Maintenance, demand, fuel conditions and commercial arrangements are possible questions to investigate, not conclusions established by a single utilisation number. Use the company's explanation and the relevant reported evidence.
Long-term contracts and short-term sales differ
Electricity can be sold under different commercial arrangements. A contract's duration, pricing structure and conditions can influence the relationship between generation, revenue and risk. A general power-price headline cannot describe every unit sold by a particular generator.
Suppose a fictional company sells 80 energy units under one arrangement and 20 under another. A price movement affecting only the second group does not automatically apply to all 100. A weighted calculation is necessary even before other terms and costs are considered.
Do not infer the actual mix from a company photograph or an industry-wide article. Read the disclosed sales categories and applicable notes. The existence of a power-purchase agreement also does not make every future payment unconditional or establish the eventual cash-collection date.
Revenue depends on quantity and realised value
More electricity sold can support revenue, but price and mix matter too. The relevant realised value should come from the company's disclosures rather than being borrowed from a household bill or an unrelated wholesale quotation. Those prices can represent different stages and conditions.
In a fictional exercise, 100 units sold at five each produce revenue of 500. Selling 110 at four produces 440. Quantity increases while the simplified revenue total falls. The calculation shows why a volume headline does not complete the financial explanation.
Actual reporting can contain additional components and adjustments. Keep the exercise separate from those records. A useful article explains the relationship without presenting an invented tariff as an actual Adani Power price or a regulated rate applicable to all customers.
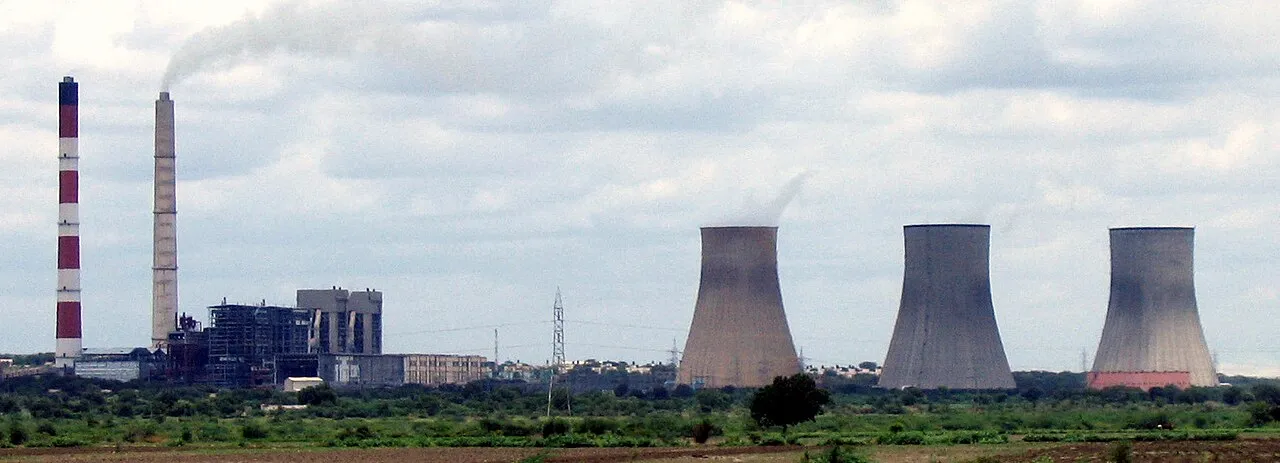
Rayalaseema Thermal Power Station in a 2007 photograph, used as industry context; this is not identified as an Adani Power asset.
Fuel cost must be read alongside revenue
Thermal generation involves fuel and other operating inputs. A change in fuel prices can affect costs, but its financial impact depends on actual sourcing, timing, contractual treatment and the reported business mix. The direction of one commodity chart is not a complete earnings forecast.
A fictional generator earns 500 and incurs fuel cost of 250 plus other operating costs of 100. Its simplified operating remainder is 150. If fuel cost rises to 300 with other assumptions unchanged, the remainder becomes 100. Real accounts require their full set of items.
The example teaches sensitivity, not a company prediction. When a results release explains a cost change, identify which period and operation it concerns. Do not generalise a specific contractual adjustment into a claim that all fuel-cost changes are automatically passed through.
Coal logistics and stocks belong to the operating context
The supply and movement of fuel can matter to generation operations. However, a public share-price article should remain within legitimate disclosed business information. It does not need sensitive site details or speculative claims about the condition of a particular facility.
For students, an inventory timeline can show opening stock, deliveries, use and closing stock using invented quantities. Starting with 40, receiving 30 and using 50 leaves 20 before other adjustments. That arithmetic differs from the cost recognised for the fuel consumed.
The exercise helps separate a physical stock from a financial expense. For the real company, use disclosed operating and accounting information. A one-day observation or social-media image cannot establish a whole quarter's fuel availability, purchasing price or financial impact.
Receivables connect revenue with cash collection
Recognising revenue does not necessarily mean receiving cash at the same moment. Receivables show amounts due under the relevant accounting record. Their movement can help explain why reported earnings and operating cash flow differ during a period.
Imagine a fictional business records 100 of revenue and collects 80 by the reporting date, with the remaining 20 outstanding under the exercise's assumptions. It has not collected all recognised sales yet. That does not independently prove that the outstanding amount is irrecoverable.
To interpret actual balances, review the notes and comparable periods. Avoid declaring a collection crisis or perfect payment performance from one isolated figure. The amount, age, counterparty information where disclosed and relevant accounting treatment can all matter to the question.
One-time items can affect a profit comparison
A period's reported profit can include items that differ from the ordinary pattern of generation activity. Their nature and accounting treatment should be read from the financial statements. Removing or annualising them without understanding the disclosure can distort the explanation in either direction.
For a fictional company, operating profit before a particular adjustment is 100 and a separately identified gain is 30. The total and the underlying components are both relevant. Calling all 130 a repeatable operating result would add an assumption not supplied by the arithmetic.
Use the actual reported measure first, then explain any alternative measure and its reconciliation. A company-defined adjusted number should remain labelled as such. Neither the adjusted nor statutory figure should be used selectively to manufacture a preferred investment story.
Financing and depreciation sit beyond a simple fuel spread
A generation plant requires substantial assets and can involve financing costs. The difference between electricity revenue and fuel expense is therefore not net profit. Depreciation, employee costs, maintenance, finance costs and other relevant items can affect the final result.
In a fictional income bridge, a gross remainder of 200 becomes 120 after operating costs, then 80 after depreciation and financing, before the remaining stated items. Each step answers a different question. Skipping the bridge makes a business appear more profitable than the defined calculation supports.
Read the labels used in the real report. An operating measure, profit before tax and profit after tax should not be presented as synonyms. The same care applies when comparing a generation business with a transmission or renewable-energy company.
Consolidation and acquisitions change comparison boundaries
A newly included business or asset can affect the scope of a group's results. Growth may combine changes in the existing operations with the addition of another operation. A comparison should identify whether both periods cover the same assets for the same length of time.
A fictional company adds a plant halfway through a year. The year's consolidated results include only the relevant contribution under the accounting record, while the following year may include a longer period. Comparing the totals without that context can overstate a simple same-asset growth interpretation.
For actual acquisitions, use the disclosed effective dates and scope. Do not assume that announced capacity, financial consolidation and full operational contribution begin on the same day. Each is a separate milestone that needs its own evidence.
Build a small power-results worksheet
Create columns for company, period, scope, capacity status, generated energy, sales quantity, revenue and operating cash flow. Add the source and unit beside every field. Mark planned figures separately so that spreadsheet formulas do not silently mix future capacity with completed output.
Next, use fictional inputs to test how quantity, realised value and fuel cost can move independently. Change one assumption at a time and explain the result. This is an exercise in understanding business relationships, not a model for predicting an actual market price.
The arithmetic fits well with class resources on percentages and units. Learners using programming courses can build a validator that rejects comparisons between megawatts and megawatt-hours or between quarterly and annual figures without an explicit conversion.
Common questions about Adani Power shares
Is installed capacity the same as electricity generated?
No. Capacity describes rated power capability; generation describes energy over a period. Operating conditions and time connect them. Keep their units and dates separate, and use reported production rather than assuming that every available unit operated continuously at its rated output.
Does a higher electricity price guarantee higher profit?
No. The company's actual sales arrangements, quantity, fuel expense and other costs must be considered. A market price may apply to a different product or transaction period. The financial statements provide the actual result; a single industry-price headline cannot replace that record.
Are all Adani companies the same investment?
No. They are distinct legal entities with their own activities and securities where listed. Confirm the company behind a quote and use that company's disclosures. Group branding does not justify combining unrelated earnings, debt or share counts into one ratio.
Where can the latest reporting scope be checked?
Use the relevant company results release and exchange filing. The dated filing identifies the reporting period and whether the accounts are standalone or consolidated. Preserve that information in any calculation, and obtain a separately timestamped exchange quote when a current market price is required.
Sources
- Adani thermal-power business overview
- Adani Power FY26 results announcement
- NSE: Adani Power October 2026 reporting identity and scope
Image credits: cover: User:Nizil Shah, source, CC BY-SA 1.0. Resized and converted to WebP. inline: Vinayaraj, source, CC BY-SA 3.0. Resized and converted to WebP.
Found an error or an outdated detail? Report a correction with the article URL and original source.