
BSE Share Price: The Exchange Business, Sensex and Revenue Explained
Distinguish BSE shares from the Sensex and exchange turnover. Learn about revenue, trading activity, bonus adjustments and financial-result comparisons.
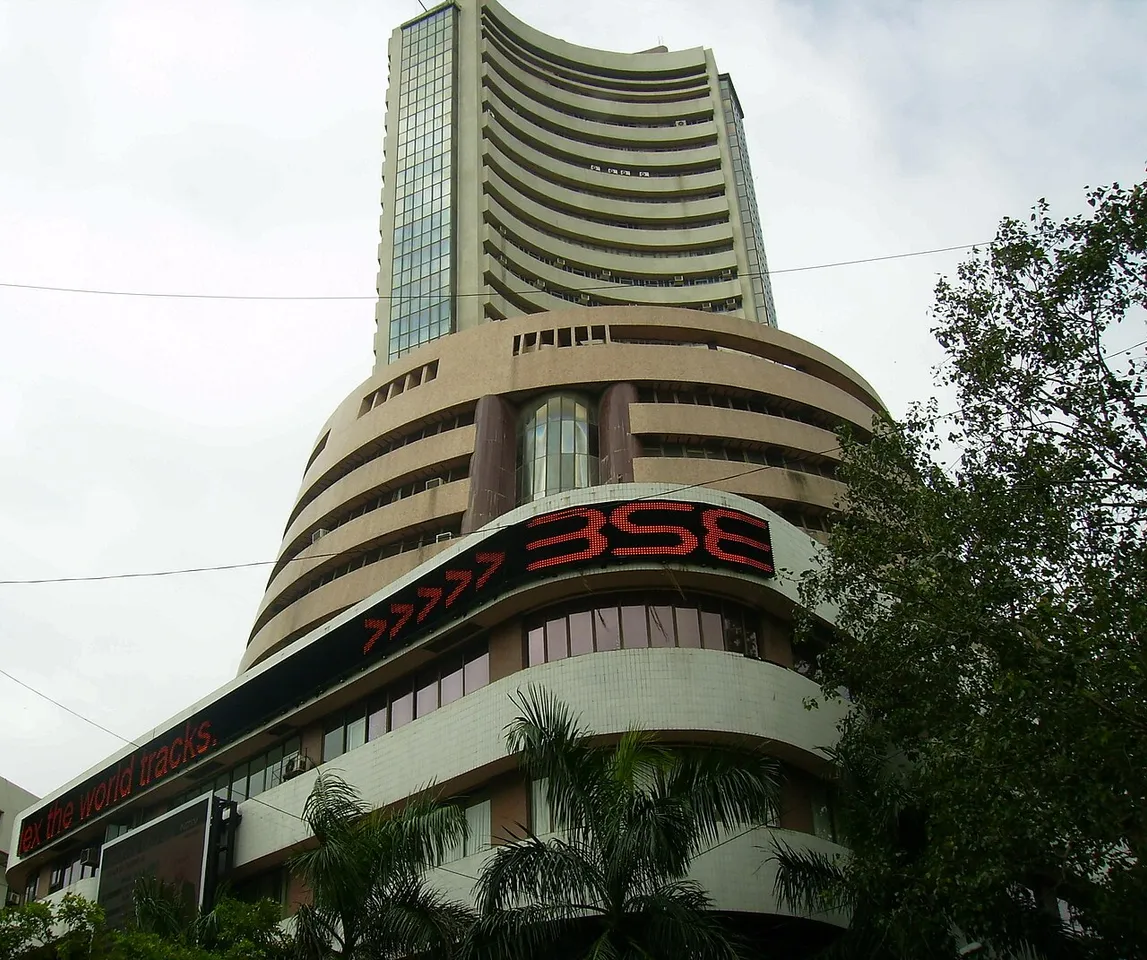
BSE Limited is an exchange business, while the Sensex is an index. A search for BSE share price should therefore identify the company's security, not substitute an index value or the price of any company traded on the exchange. NSE's official quote page identifies the listed company under the symbol BSE.
This guide is not a live quote or a trading recommendation. It explains how an exchange earns and reports money, why trading activity is not the same as exchange revenue, and how a corporate action can change a per-share chart. Use an exchange timestamp for the current price and the company's filings for its actual results.
BSE Limited, the exchange and the Sensex
These names are related but answer different questions. The company operates exchange-related businesses. The exchange provides a market infrastructure context for securities. An index measures the performance of a defined basket under its methodology. An index level is not the amount someone pays for one BSE Limited share.
| Search or measure | What to identify |
|---|---|
| BSE Limited share | Exact listed company and quote |
| Sensex level | Index value and timestamp |
| A security traded on BSE | That issuer's own identity |
| Exchange activity | Product, period and volume definition |
| BSE earnings | Reporting scope and financial statements |
A useful comparison begins by naming the object. A number can be perfectly accurate and still answer the wrong question. Putting a large index value beside the phrase share price creates confusion even if the index itself was copied correctly from an official screen.
Where to begin a company quote check
NSE's company page supplies the relevant listed-company route for BSE Limited. Keep the symbol, date, time and price type together. Do not assume that a company with exchange in its history has its shares quoted in every market whose name appears in its business description.
The previous close, last traded price and closing price are different entries. A market screen can show several at once. A report that selects one should name it rather than use a vague current value label. A screenshot from a prior session should retain its date instead of being refreshed only in the surrounding headline.
For students, make a small identity sheet before doing arithmetic: company, security, exchange, currency and timestamp. Then record the source. This prevents an index, a listed company and a trading venue from being merged into one number simply because they share a familiar abbreviation.
An exchange's activity is not its own trading portfolio
An exchange can facilitate market activity without owning every security traded through its systems. The total value of transactions is not automatically revenue earned by the exchange. The company's actual fees, services and financial scope determine its reported income.
An original fictional example illustrates the difference. Suppose transactions worth 1,000,000 units pass through a platform and a defined fee is 100 units under the applicable arrangement. The platform's fee is not 1,000,000. The transaction value describes the activity; the fee describes a particular revenue component in the example.
Real exchanges have more complex schedules and businesses. The example is not a BSE fee quote and should not be used to calculate an actual bill. It teaches the basic distinction that a high turnover figure cannot simply be copied into a company's revenue column.
Volume, turnover and notional value need definitions
Market reports can discuss contracts, transaction value or other activity measures. The definitions differ by product. A count of contracts and a currency amount are not interchangeable, and a derivatives notional measure should not be treated as cash received by the exchange.
Before comparing two headlines, ask whether they use the same product and unit. A large percentage change in one segment does not establish an identical change across the whole business. Aggregating unlike units can create an impressive-looking total without a useful interpretation.
For a classroom data exercise, keep count, value and fee in separate columns. Add the period and source definition to the heading. Then test how an increase in activity affects a fictional fee under a stated formula. The exercise is about reading business data, not recommending a derivatives trade.
Product mix can change the revenue relationship
Different products and services can have different fee arrangements. If the mix of activity changes, revenue need not grow at the same rate as a single headline volume measure. A careful review uses the actual disclosures rather than assuming one constant conversion from all market activity to income.
Imagine a fictional platform with two services. One produces ten fee units per event and another produces one. A shift toward the second can increase event counts while changing average fee income. The arithmetic demonstrates the effect of mix, not BSE's actual pricing or a forecast of its revenue.
This explains why an investor presentation should be read alongside the statements. Management may highlight a fast-growing activity, while the financial accounts show its contribution within the larger business. Both can be informative when their scopes remain clear. Neither should be used to erase the other.
Reporting periods and the November results context
The official exchange event calendar identifies a BSE Limited financial-results meeting on 4 November 2026 for the period ending 30 September. A meeting date, a results publication and a market-price reaction are separate records. This guide does not manufacture a closing quote or a causal price move from the calendar entry.
Use the actual filing for the resulting financial numbers. A news headline may summarise them, but the primary statement supplies the reporting scope, units and notes. If a value cannot be matched to that record, leave it out rather than choose a convenient number from an unrelated quarter.
Quarterly and half-year figures can appear in the same release. Preserve the duration when comparing them. A six-month total is not a quarterly total, and a year-on-year comparison needs the corresponding period. The dates are part of the calculation, not decorative information above the table.
Operating revenue and other income
Financial statements can separate revenue from operations and other income. Those labels describe different components of the reported total. A change in one component should not be attributed automatically to transaction activity without checking the statement and notes.
For a fictional example, operating revenue of 100 and other income of 20 produce 120 in the simplified total. If the second component later rises while the first is unchanged, the overall increase does not mean the operating activity grew by the same percentage. The category distinction is essential to the explanation.
Do not treat the example as BSE's reported amounts. It is a method for asking a better question: what changed, and in which line? That question is more informative than describing every increase in total income as proof of higher trading fees.
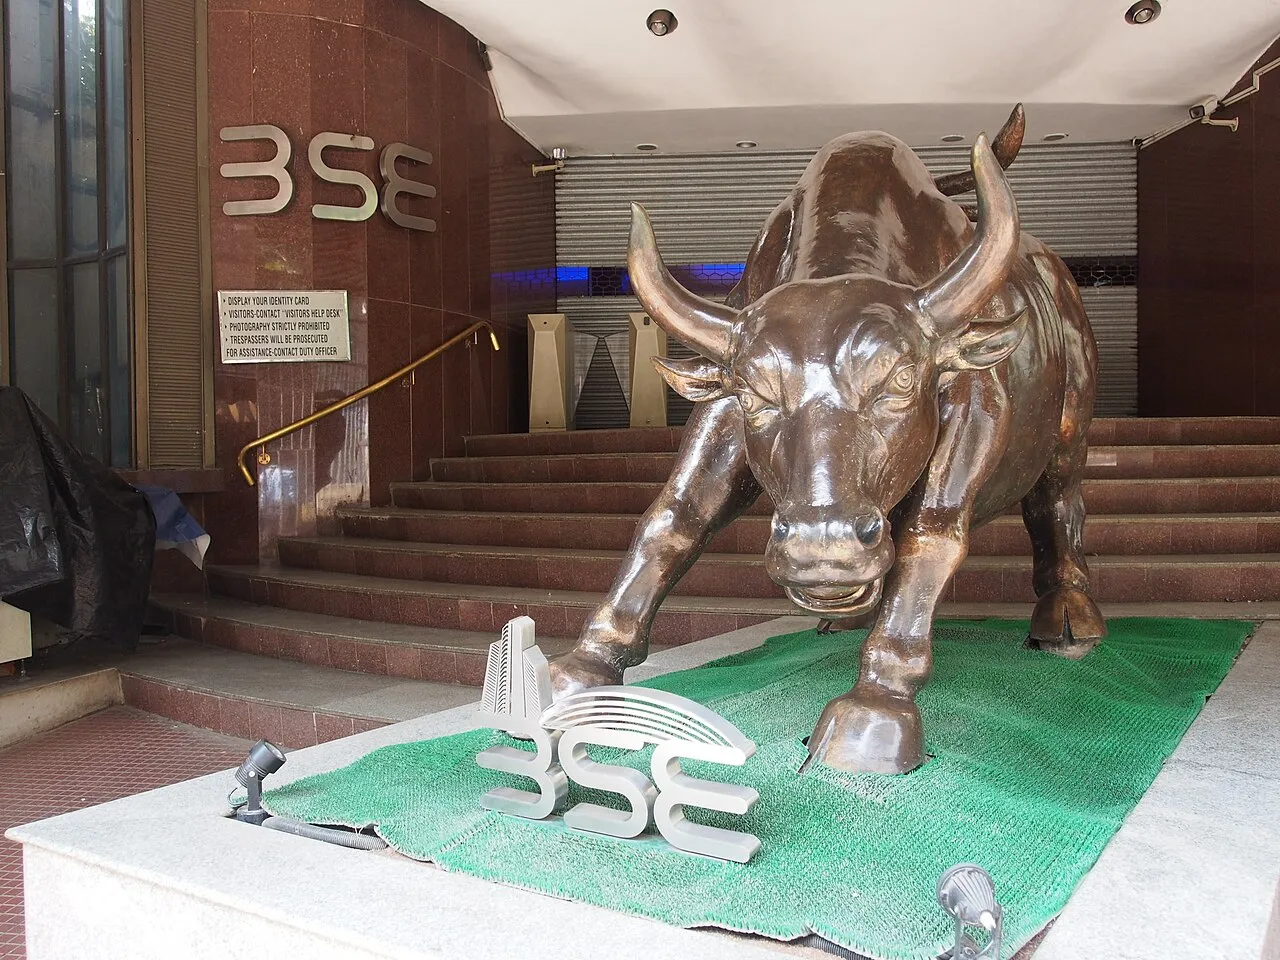
The bull statue outside BSE in Mumbai, shown as market symbolism rather than a prediction of future returns.
Consolidated and standalone numbers can differ
A consolidated statement and a standalone statement cover different reporting scopes. Subsidiaries and other relevant accounting relationships can affect the difference. Read the heading before comparing a number from one scope with a number from the other.
An article should not add the two totals together as if they were independent businesses. That can double-count amounts already included in the consolidated presentation. Likewise, a subsidiary's activity does not automatically equal a separately distributable amount for every shareholder of the parent.
For student work, put standalone and consolidated tables on clearly labelled sections. Use the notes to understand the relationship rather than force the numbers to match. The aim is to preserve the reporting definitions, not simplify them away to make a chart look cleaner.
Why profit and transaction activity can move differently
Costs, business mix, other income and accounting adjustments can influence profit alongside revenue. A rise in activity does not guarantee that every margin improves. The financial statement provides the actual relationships; a volume headline alone does not.
In an invented model, revenue rises from 100 to 120 while costs rise from 70 to 100. The simplified difference changes from 30 to 20. There is no contradiction between revenue growth and a lower difference under those assumptions. A reader needs both sides of the calculation.
The example explains a possibility, not BSE's actual result. Do not attach an invented cost pattern to the company. Use the model to understand why a complete review examines revenue, defined profit measures and their notes rather than treating one activity percentage as the answer to every financial question.
The bonus-share example: more shares do not automatically mean more wealth
BSE's May 2026 filing describes a 2025 bonus allotment in the ratio of two additional equity shares for one held, with a May 2025 record date. That historical corporate action should be kept separate from a new dividend or a current market-price claim.
The arithmetic of such a ratio is useful. In a simplified example, ten original shares plus two additional shares for each original produces thirty shares. The larger count alone does not establish three times the economic value. The comparable per-share reference and market pricing need to be considered under the actual corporate action.
This is why a historical chart may require adjustment. An unadjusted per-share step can look like a sudden loss if the additional shares are ignored. Before explaining a dramatic movement, check the company's corporate-action record and the chart methodology rather than assume that the business changed by the same proportion.
Earnings per share needs the correct denominator
Earnings per share relates a defined earnings amount to the relevant share count under the applicable accounting measure. A change in share count can affect the per-share figure and the presentation of historical comparisons. Read basic and diluted labels rather than treating every EPS value as identical.
For a fictional company earning 300 units across 100 shares, a simple per-share calculation gives three. If a purely illustrative share-count change is introduced, the comparison needs the appropriate adjustment. The example is not an official BSE EPS calculation; actual statements supply their own denominators and treatment.
Keep total earnings and per-share earnings in different columns. A per-share chart cannot explain the total business without the denominator, just as a nominal share price cannot establish market value without a share count. Clear units make a financial comparison much harder to misread.
Market expectations are not a guarantee
A company's operating performance and its market price are related topics but different records. Prices can reflect expectations about future activity, costs and many other factors. A strong past result does not create a guaranteed price path, and a price decline does not independently disprove a correctly reported result.
Avoid a single-cause explanation unless the evidence supports it. An announcement and a price movement occurring close together establish timing, not every participant's reason for trading. Attribute an analyst's interpretation rather than present it as a measured fact about the whole market.
This guide does not assign a fair value or a target. It supplies a framework for reading the company's evidence. A useful educational page can make a market search more understandable without telling every reader to make the same transaction or inventing certainty about future returns.
Build a clean exchange-business comparison sheet
Start with the legal entity and reporting period. Add separately labelled operating measures, financial amounts and per-share figures. Keep currency scales explicit. A value in lakhs and one in crores should not sit side by side without conversion or a clear heading.
Store the source alongside each period and preserve any restatement. If a metric's definition changes, note it before drawing a continuous trend line. A chart that joins incompatible definitions can mislead even when every number was copied faithfully from a source.
Use fictional data first to test formulas. Confirm that volume does not automatically populate revenue and that a corporate action does not simply multiply wealth. These checks make a spreadsheet or small programme more useful than a polished dashboard built on confused categories.
Questions about BSE share-price searches
Is the Sensex the price of BSE Limited?
No. An index level and a company's share quote are different measurements. Use the exact listed-company page for the share and the appropriate index record for the Sensex. Their relationship does not make their numbers interchangeable.
Is transaction turnover the exchange's revenue?
No. Activity and revenue require different definitions. The fictional examples explain why a platform facilitating a transaction does not automatically earn the entire transaction value. Use the company's statements for actual income and fees.
Where can learners practise these concepts?
Explore class resources for percentages and units or programming courses to build a clearly labelled comparison tool. Begin with the official company quote, reporting calendar and financial filing below rather than an unsupported live-price or target claim.
Sources
- Source: NSE BSE Limited company quote and disclosure route
- Source: Official financial-results event calendar
- Source: BSE Limited May 2026 filing and historical bonus information
Image credits: cover: Niyantha Shekhar, source, CC BY 2.0. Resized and converted to WebP. inline: Pradeep717, source, CC BY-SA 4.0. Resized and converted to WebP.
Found an error or an outdated detail? Report a correction with the article URL and original source.