
Cummins India Share Price: Engines, Exports and Financial Results
Read Cummins India shares through the listed entity, engines, power systems, exports and cash flow, with clear examples and official investor sources.
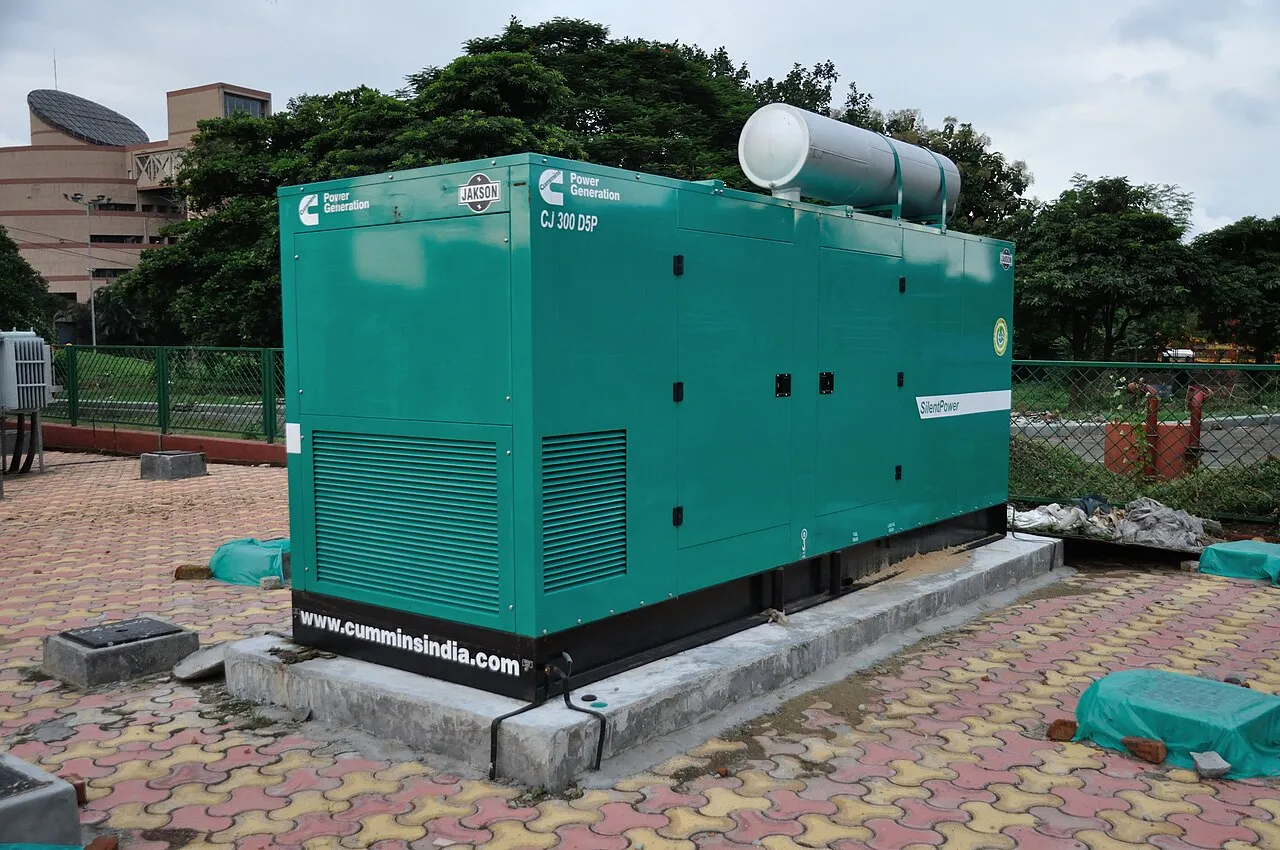
Cummins India Limited is the listed Indian company behind the NSE symbol CUMMINSIND and BSE code 500480. It should not be confused with the US-listed Cummins Inc. or every other company in the wider Indian group. A share-price check needs the correct entity before its quote or financial statements can be interpreted.
This page does not supply an invented live quote or a price target. It explains the engine and power-systems business, the financial records to use and the difference between industrial demand, reported sales and cash generation. The company's official investor overview and financial library are the starting sources, checked on 6 November 2026.
Which company does the share-price search mean?
The official investor overview identifies Cummins India Limited and publishes its exchange identifiers. It also describes Engine, Power Systems, Components and Distribution as business units. Those labels help explain the company, while figures for another group entity should not be silently inserted into the listed company's accounts.
| Identity check | Official reference |
|---|---|
| Listed company | Cummins India Limited |
| NSE symbol | CUMMINSIND |
| BSE code | 500480 |
| Different listed entity | Cummins Inc. in the United States |
| Business context | Engines, power systems, components and distribution |
| Financial source | India financial-results library |
The distinction is more than a naming detail. A brand can operate through several legal entities with different assets, owners and reporting scopes. A headline about the wider group can be relevant context without becoming revenue or profit earned by the particular listed company a reader is researching.
Start a quote check with the exchange and time
A last traded price, the previous close and a session's closing price are different fields. Record which one is being discussed and when it was observed. An old screenshot can remain online after the market moves; a recent upload does not turn its contents into a current quote.
Keep the currency and market with the number. The US parent's share price and the Indian company's share price are not alternative quotations for the same security. Their reporting currencies, share counts and business scopes differ. A conversion of one quote does not create the other company's market price.
For a student research sheet, use separate columns for company, identifier, exchange, timestamp and price type. Then add the source link. That structure prevents a correct-looking number from being attached to the wrong instrument and makes later comparisons reproducible.
What an engine manufacturer sells
The official overview describes engines serving commercial-vehicle and off-highway uses, with power systems and related components and support. The business is therefore not adequately described by a single consumer-product price. Different applications can involve different specifications, customers and demand patterns.
An engine, an integrated generator set and a service activity are also different products or activities. Their revenue and cost characteristics need not be identical. A rise in one area does not automatically establish the same growth rate across every business unit. Read the company's actual disclosures before assigning a universal trend.
Do not infer a contract win from a photograph of equipment bearing the brand. A product can appear at a customer site without establishing the date, seller entity or financial value of a transaction. Public contracts and financial statements require their own records rather than a visual association.
Backup demand and continuous operation are different contexts
A standby system and equipment intended for extended operation answer different customer needs. A factory, a hospital and a construction site may use power equipment under different conditions. Those differences can influence product selection and service requirements, but this guide does not provide installation instructions or a specification for a particular site.
For financial reading, the important point is demand mix. A business selling into several applications can experience different cycles at the same time. It is too simple to assume that one headline about electricity supply or infrastructure spending fully explains every part of the company's order flow.
A useful analysis asks what the company actually disclosed about end markets and the period covered. Distinguish an industry opportunity from a booked order, and a booked order from a delivered product. The sequence matters even when the market theme sounds compelling.
Power ratings: why kW and kVA need labels
Technical specifications can use kilowatts and kilovolt-amperes, which describe different electrical quantities. A reader should not compare the displayed numbers as though the units were interchangeable. The relevant assumptions and product conditions belong with any conversion.
In a simplified fictional calculation, 100 kVA at a stated power factor of 0.8 corresponds to 80 kW of real power. This is a teaching example, not a Cummins product rating or advice for selecting equipment. Without the needed condition, a bare conversion would be incomplete.
The financial lesson is broader: industrial volume measures and monetary values also use different units. A table of equipment ratings does not directly supply sales revenue or a market valuation. Read each measure for the question it answers instead of treating every large number as a comparable indicator of business scale.
Domestic sales and exports require separate reading
A company can discuss domestic and export activity within the same release. Their growth rates may differ, and the combined result depends on the relative size of each category. A strong percentage in a smaller category does not necessarily dominate the total.
Consider a fictional business with domestic sales of 80 units and exports of 20. If domestic sales stay unchanged while exports rise to 30, total sales rise from 100 to 110. Export growth is 50 percent, while total growth is ten percent. Both calculations are correct because their denominators differ.
These figures are not Cummins India's results. They show why a headline about one segment should not be pasted onto the whole company. For actual figures, use the same reporting period, definitions and currency units from the financial statements.
Currency can affect comparisons without changing the physical product
When a business reports international activity, currency translation and transaction exposure can matter. A rupee-denominated value and a value in another currency should not be compared without a stated basis. This does not establish that a particular currency move produced a particular quarterly result; that needs the company's actual disclosures.
For an original example, imagine a sale of 100 foreign-currency units. Converting it at two hypothetical rates produces different reporting-currency values even though the original foreign amount is unchanged. The example explains a mechanism, not a forecast or a claim about the company's hedging arrangements.
Read any disclosed currency effects alongside volumes, pricing and costs. A financial result can reflect several influences at once. An article should not use a convenient exchange-rate story as the sole explanation for a change that has not been reconciled from the actual statement.
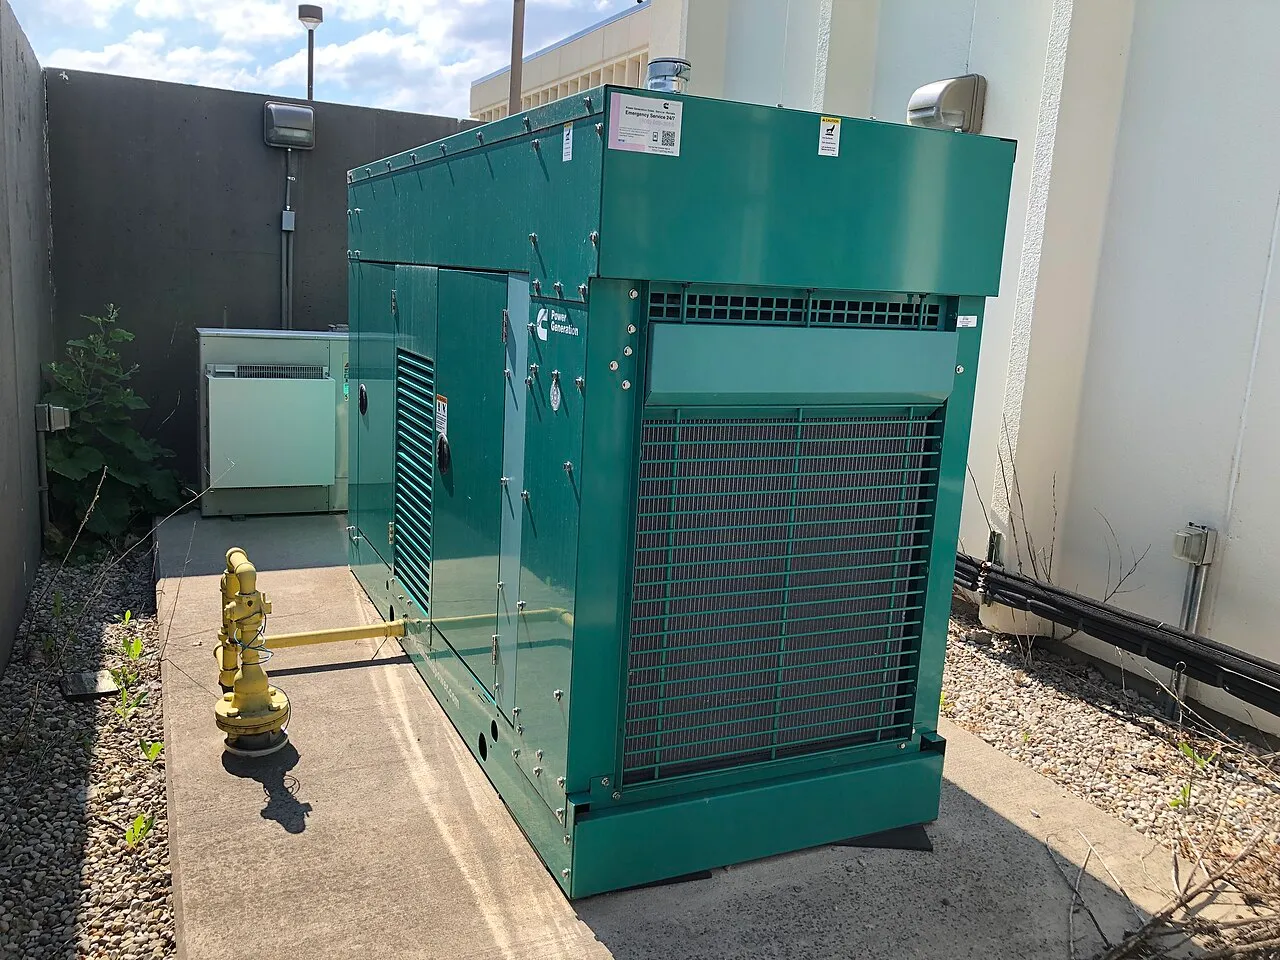
A credited Cummins generator photograph, shown as equipment context rather than evidence of a new Cummins India order.
Revenue, operating profit and net profit are different lines
Revenue measures a defined top-line accounting amount. Operating profit and net profit represent different stages after the applicable costs and adjustments. A sales increase does not guarantee an equal percentage increase in either profit measure. The labels and notes are essential to the comparison.
In a fictional illustration, revenue of 100 and operating costs of 85 leave 15 before other items in that simplified model. If revenue rises to 110 and those costs rise to 98, the difference becomes twelve. Higher revenue and lower simplified operating profit can coexist without an arithmetic contradiction.
The example is not a description of Cummins India's margins. It shows why a serious review should examine the actual cost and profit measures rather than repeat one growth percentage as if it described every part of the business. Preserve exceptional items and other relevant notes instead of removing them to make a trend smoother.
Distribution and service deserve attention
The official overview includes a distribution business supporting equipment through parts and service activities. That is a different context from counting newly manufactured engines alone. An installed equipment base can create support needs, but a writer should not invent the value or timing of those future services.
For analysis, ask how the company defines and reports the relevant activity. A broad statement about aftermarket potential is not the same as recognised service revenue. Nor does a large installed base automatically establish a fixed future profit from each unit. Actual utilisation, arrangements and costs matter.
Students can model a fictional equipment sale and a later service event as separate transactions. Keep the product, date and amount visible. The exercise demonstrates how a business relationship can extend over time without treating all possible future activity as revenue already earned today.
Cash flow and working capital add another dimension
Profit and cash generation can diverge over a period. Inventory, customer receivables, supplier payments and other items affect the cash position. A quarter with strong reported profit should therefore be read alongside the cash-flow information rather than assumed to have produced an identical cash inflow.
For an industrial company, production can require materials and work before a customer pays. That general sequence explains why working-capital accounts matter. It does not establish that any particular receivable is overdue or that a specific customer has failed to pay. Those would be separate claims needing evidence.
A useful worksheet separates the income statement, balance sheet and cash-flow statement. Compare their defined periods and scopes, then identify the bridges between them. The goal is not to force every figure to match, but to understand why the statements measure different aspects of the same business.
Capital expenditure is not automatically an immediate expense
Spending on productive assets and an ordinary period expense can have different accounting treatment. The financial statements and notes explain the actual treatment. A headline about an investment amount should not be subtracted casually from quarterly profit to create an unofficial earnings figure.
The timing of benefits is another question. A capacity project can require planning and execution before affecting output. Announcing an investment does not itself prove that additional capacity is operating or that customer demand will fill it. Keep announced plans, completed assets and measured outcomes in separate columns.
For a classroom project, use fictional dates and amounts to show a planned asset, completion and later use. Label the assumptions. This teaches the sequence without claiming to know the company's confidential project economics or promising a return from an announced expansion.
Compare the right reporting periods
The financial library organises releases by quarter and year. Read the period ending date and whether the figures are standalone or consolidated. A quarter, a half year and a full year should not be placed in one growth comparison without explaining the different durations.
Also preserve units such as lakhs, crores and millions. A copied number without its scale can be wrong by a large factor even when every digit was transcribed correctly. Keep the unit in the table heading and make conversions explicit rather than silently changing the scale midway through a calculation.
If a prior period has been restated, use the comparable figure identified in the current report and note the change. A comparison between an original old presentation and a newly defined current measure may not be like for like. Good source work is part of the calculation, not something added afterward.
A lower nominal share price does not mean a cheaper company
Price per share needs the share count and the relevant financial context. Two companies can have very different numbers of shares. Comparing their nominal prices alone is not a comparison of their market values, profitability or valuation relative to a defined measure.
For a fictional example, 100 shares at ten units each have the same simple market value as ten shares at 100 units each. The different per-share prices do not establish which business is better or which investment suits a particular person. A valuation question requires additional inputs and assumptions.
This guide does not provide a buy, sell or target-price instruction. It explains the company's identity and the records needed to understand a quote. A precise target without a stated method would create false confidence rather than add useful educational information.
Questions about Cummins India shares
Is CUMMINSIND the US parent company's ticker?
No. The official Indian overview identifies CUMMINSIND with Cummins India Limited. Cummins Inc. is a different listed entity. Keep the legal company, exchange and reporting scope together before comparing prices or financial figures.
Does every Cummins-branded activity belong to the listed Indian company?
Not automatically. The official overview distinguishes several group entities and identifies the particular listed company. Use its own statements for its financial results rather than treating every group announcement as part of the same accounts.
Where can learners practise the calculations?
Explore class resources for percentages and units or programming courses to build a small financial-table checker. Keep fictional examples separate from the company's figures, and use the official library below for actual reporting periods and disclosures.
Sources
- Source: Cummins India official investor overview and exchange identifiers
- Source: Cummins India financial statements
Image credits: cover: Biswarup Ganguly, source, CC BY 3.0. Resized and converted to WebP. inline: Mbrickn, source, CC BY 4.0. Resized and converted to WebP.
Found an error or an outdated detail? Report a correction with the article URL and original source.