
Suzlon Share Price: Wind Orders, Revenue and Cash Flow Explained
Understand Suzlon shares through dated order-book figures, wind capacity, revenue and cash flow. Learn what official filings can and cannot establish.
A Suzlon share-price search should begin with a dated exchange quote and the correct company record. This page is not a live price feed and does not invent an intraday rate. It explains the business information behind the search, including Suzlon's 29 October 2026 Q2 FY27 release, which reported 26 percent year-on-year revenue growth.
The same release described first-half order intake above 1.5 GW and an order book above 6 GW. Those are company-reported operating measures, not a guaranteed future profit or a price target. Understanding how orders, deliveries, revenue and cash differ is more useful than assuming that one positive headline dictates the next market move.
What should a Suzlon price check include?
Record the company, exchange, timestamp, currency and type of price. A last traded price, previous close and closing price are different fields. A screen captured during trading should not be presented as the final close, and a quote from a different day should not be relabelled today simply because the page was refreshed.
| Information | Why it matters |
|---|---|
| Exact listed company | Avoids confusing a brand with another entity |
| Exchange and timestamp | Defines the quote being discussed |
| Reporting period | Keeps a quarter separate from a half year |
| Order intake | Describes new business booked under the stated definition |
| Order book | Describes the reported outstanding pipeline |
| Deliveries and revenue | Describe execution and accounting outcomes |
| Cash flow | Shows a different dimension from reported profit |
The table is a research checklist, not a recommendation. A share-price article should make its evidence traceable before attempting an explanation. Without a timestamp and a matching event, a statement that a stock rose because of one announcement is a hypothesis rather than an established causal account.
What the October results announcement establishes
Suzlon's dated company release concerns Q2 FY27. Preserve that label when comparing it with another period. The first-half order figures cover a different span from the single-quarter revenue comparison. They can appear in the same release without measuring the same interval or the same activity.
The source also contains management's interpretation of the business. A reader can report that interpretation while distinguishing it from an independent evaluation. A company announcement establishes what the company reported; it does not automatically validate every forecast an outside commentator attaches to it.
Do not mix the October Q2 release with an earlier Q3 FY26 or Q4 FY26 presentation merely because a search result supplies a larger number. The financial year and quarter are part of the statistic. An impressive figure from the wrong period would make a comparison less accurate, not more informative.
Wind-turbine capacity is not the same as energy produced
Wind businesses use capacity measures such as megawatts and gigawatts. These describe a power rating or a stated capacity measure, not the energy produced during every hour. A capacity figure and a period's generation must remain distinct, just as a car's tank size is not the distance already travelled.
For a fictional example, a 2 MW installation operating at its full stated power for three hours would produce 6 MWh. The example's constant full-power assumption is deliberately simplified. It is not a generation estimate for a Suzlon project, and it should not be used to promise output under actual wind conditions.
The lesson is to retain units. MW, GW and MWh are not interchangeable labels attached to large numbers. When comparing an order-book capacity with an energy-generation report, first ask whether the quantities measure the same thing. Otherwise the comparison is invalid before any arithmetic begins.
Order intake and order book answer different questions
Order intake concerns new orders during a period under the company's reporting definition. An order book is the reported outstanding pipeline at a point or under the stated scope. A strong intake can add to that pipeline, while execution and other changes can reduce or alter it.
An original fictional model starts with an order book of 100 units, adds 30 units of new orders and removes 20 units delivered. Under those simplified assumptions, the closing pipeline is 110. Real reporting can contain additional adjustments, so the model is a way to understand categories rather than a reconstruction of Suzlon's accounts.
Do not add a closing order book to the period's deliveries and call the sum revenue. The capacity and accounting units may differ, and the measures describe different stages. A useful business explanation follows the route from agreement to execution rather than treating every announcement as immediate completed sales.
Why an order does not become cash immediately
A contract, a delivery, recognised revenue and a customer payment are different events. Their timing depends on the actual agreement and accounting treatment. A press release naming a large pipeline does not by itself establish that all the associated cash has already arrived or that the full amount will be recognised in the next quarter.
For an industrial company, working capital helps explain the gap. Inventory, receivables and payables can change as production and delivery proceed. A business can report profit while cash collection follows a different pattern. That is why the cash-flow statement belongs beside the income statement in a serious review.
No contract-specific payment schedule is assumed here. Readers should use the company's financial statements and notes for actual terms and balances. The general principle is enough to avoid a common error: a pipeline headline is not a bank balance and should not be presented as one.
Deliveries make execution visible, but need a definition
A delivery measure can help show progress from pipeline to executed work. Read what the company includes in that measure and the period it covers. A comparison between a quarter and a half year will be misleading if both are presented as equivalent quarterly totals.
Also distinguish a volume measure from a value measure. Delivering more capacity does not automatically establish an identical percentage increase in revenue or profit. Product mix, contractual pricing, timing and costs can affect the relationship. Those factors should be examined from actual disclosures rather than assumed to move proportionately.
For students, create a fictional table with units delivered, revenue and cost. Change the average selling value while holding volume constant, then observe revenue. Next change cost while holding revenue constant. The exercise shows why a single operating number cannot explain every line in a financial statement.
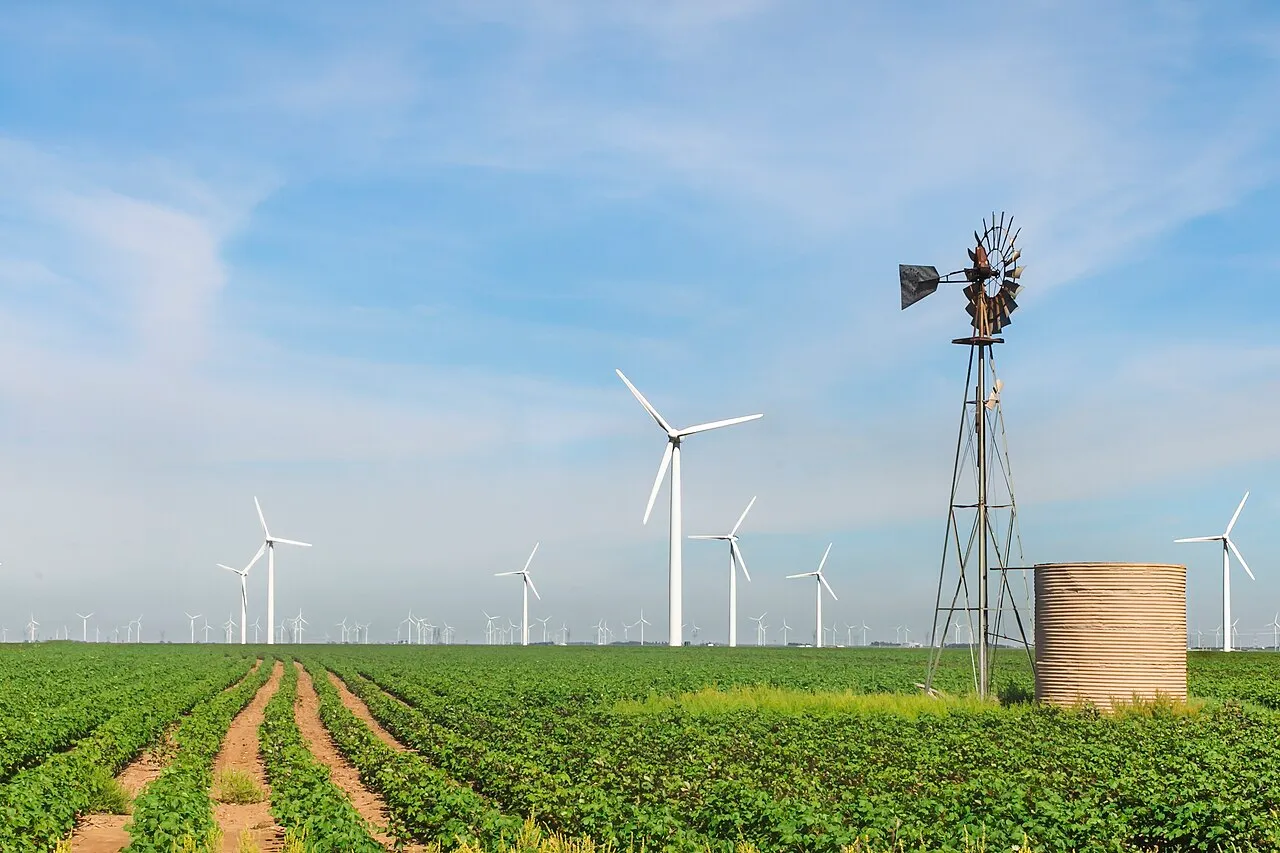
Roscoe Wind Farm in Texas, used only to illustrate wind generation; this is not identified as a Suzlon project.
Revenue growth is not profit growth
The reported 26 percent revenue increase is a year-on-year comparison in the cited quarterly release. It should not be renamed a 26 percent share-price gain, profit increase or cash-flow improvement. Each of those would require its own figures and definition.
In a fictional business, revenue rising from 100 to 126 gives 26 percent growth. If costs rise from 90 to 120, the simple difference falls from ten to six. The revenue statement remains true while the simplified profit measure declines. These invented figures illustrate the distinction, not Suzlon's actual cost structure.
Read the relevant margins and notes before drawing a conclusion about profitability. A margin divides a defined profit measure by revenue; different profit measures produce different margins. A table that drops the label can make operating profit, earnings before selected costs and net profit look interchangeable when they are not.
Market value and operating capacity use different units
A share price is an amount per share. Market capitalisation combines price with the relevant share count. Neither is measured in megawatts. A company reporting a larger capacity pipeline has not directly reported its market capitalisation, even if both figures appear in the same news article.
For a simplified fictional company with 100 shares at ten currency units each, market capitalisation is 1,000 units. If the share count changes, the same price can correspond to a different market value. That is why a nominally low-priced share is not automatically a cheaper business than a higher-priced share of another company.
Avoid comparing prices alone as a measure of value. A meaningful comparison needs the share count, financial scope and relevant business measures. This guide does not calculate a fair value or recommend a trading decision; it explains the inputs that a price headline leaves out.
Corporate actions can change the appearance of a chart
A split, bonus issue or other corporate action can affect per-share figures and historical chart presentation. Before treating a visible step as a business collapse or a sudden creation of wealth, check the exchange's corporate-action record and whether the chart is adjusted.
For a fictional two-for-one split, a holding of ten shares might become twenty under the stated arrangement while the comparable per-share price adjusts. Doubling the share count alone does not double the economic value of the holding. The action's actual terms and market response must be kept separate.
This is a general example, not a claim that Suzlon has announced that action in the period discussed. The habit is to check the record before explaining a chart. A mathematical adjustment and a genuine market-price movement can occur near each other without being the same event.
How to read a results comparison sheet
Use one row per reporting period and separate columns for the measures you intend to compare. Include whether the figures are standalone or consolidated, the currency unit and any restatement. A number in lakhs and a number in crores should not be compared as though the displayed values use the same scale.
Keep original values and calculated changes in different columns. Calculate a year-on-year percentage only when the base and current periods are comparable. If the base is zero or otherwise unsuitable for a normal percentage calculation, describe the limitation rather than produce a dramatic but meaningless growth rate.
Store the source URL and publication date with the row. That makes a later correction manageable and helps another reader reproduce the calculation. A neat spreadsheet without traceable inputs is less useful than a plain table with clear definitions and sources.
A price move needs more than a convenient explanation
Markets can respond to several pieces of information at once. A results announcement, broader sector movement and changing expectations may overlap. Observing a price move after an announcement does not, by itself, establish that the announcement is the sole cause.
A careful account names the event and describes the observed timing without claiming access to every participant's reasoning. If an explanation comes from an analyst or management, attribute it. Do not present a plausible story as a measured fact simply because it fits the direction of the chart.
The same discipline applies to negative claims. A falling quote does not prove that reported orders are fictitious, and a rising quote does not verify every forecast. Business evidence and market behaviour should be examined together while remaining distinct records.
Questions about Suzlon share-price searches
Does this page provide today's live quote?
No. Use a dated exchange quote for the current market figure. This guide explains the operating and financial information behind the search. It does not relabel an old closing price as a live rate or provide an unsupported target.
Is the order book guaranteed future profit?
No. A reported pipeline describes a different stage from recognised revenue, profit and cash collection. Read execution, costs and financial notes alongside the pipeline. The fictional models above show how those categories differ without claiming to predict an actual outcome.
Where can students practise the concepts?
Use class resources for ratios and financial tables or programming courses to build a small comparison calculator. Keep invented exercises separate from company figures. For Suzlon's actual disclosures, begin with the dated company release and its financial-report library below.
A practical reading notebook should also record whether a figure is provisional, audited or subsequently revised. When two releases appear to disagree, check their scope and dates before deciding that either is wrong. An annual consolidated figure and a quarterly standalone figure answer different questions. Keeping those labels beside the numbers makes later comparisons easier and prevents a persuasive screenshot from replacing the underlying evidence.
Sources
Image credits: cover: SuyogJoshiPhotography, source, CC BY-SA 4.0. Resized and converted to WebP. inline: Matthew T Rader, https://matthewtrader.com, source, CC BY-SA 4.0. Resized and converted to WebP.
Found an error or an outdated detail? Report a correction with the article URL and original source.