
Nasdaq-100 Explained: Scope, Modified Weighting and Quote Comparisons
Understand Nasdaq-100 scope, company and security counts, modified weighting and return versions, with labelled examples for reading market quotes.
The Nasdaq-100 Index measures a defined group of large non-financial companies listed on Nasdaq, using a modified market-capitalisation weighting method. It is not the same thing as the Nasdaq exchange or every company traded there. Understanding the benchmark requires identifying its scope, the version of the index and the period attached to a performance figure.
This guide was checked on 5 November 2026 against Nasdaq's official overview and methodology. It uses invented examples to explain arithmetic and interpretation. It does not provide a live quote, forecast a return or recommend a fund or security. Current constituents and calculation rules should be checked in the administrator's applicable information.
What does the Nasdaq-100 represent?
Nasdaq describes the index as covering one hundred of the largest Nasdaq-listed non-financial companies under its rules. The official description includes several industries, rather than defining the benchmark simply as every technology company. Read the actual scope instead of substituting a convenient nickname for the methodology.
Begin a comparison by writing the population represented by each measure. An exchange, an index and an investment product can share a familiar name while answering different questions. Knowing which of these a page describes is more important than assuming that every number labelled Nasdaq has an identical meaning.
For a classroom task, create three boxes: marketplace, benchmark and product. Put an invented example in each and explain the relationship. This makes later discussions clearer because students can ask which record they are reading instead of using one name for several distinct concepts.
Why can the number of securities differ from the company count?
A company and a security issued by that company are different things. Nasdaq's methodology includes provisions concerning eligible share classes. A benchmark described by its company count can therefore require more careful reading than assuming that every displayed component count must be numerically identical to the name of the index.
Use an invented example with two companies, one represented by two eligible classes and the other by one. The exercise contains two companies but three securities. It illustrates a counting distinction and should not be presented as the actual current composition of the Nasdaq-100.
When comparing a factsheet with a headline, check what each count measures. A difference can arise from definitions rather than an error. Preserve the labels company, class and security where they matter, and consult the current methodology before drawing a conclusion about a particular component list.
What does market capitalisation weighting mean?
Market capitalisation connects a share price with a relevant share quantity. A market-capitalisation-weighted approach uses defined size measures in determining weights, while the actual Nasdaq-100 method applies its own rules and modifications. Do not replace the published methodology with an unqualified assumption that every detail is captured by one simple formula.
For a toy exercise, use three invented capitalisation values: 100, 200 and 700 units. Their total is 1,000, giving simple proportional weights of ten, twenty and seventy percent. These are teaching values for a basic relationship, not the real index weights or its modification rules.
Now change the largest invented value while holding the others constant. Observe how the proportions change. The exercise helps explain why a movement in a heavily weighted component can matter differently from the same percentage movement in a smaller component, without claiming to reproduce the complete benchmark calculation.
Why does modified weighting matter?
The word modified signals that the administrator's actual rules must be read, including the relevant adjustments and constraints. A basic capitalisation diagram is a starting point, not a complete description. Use the current methodology for a claim about how a particular weight or change is determined.
In a classroom model, compare a purely proportional arrangement with an invented arrangement that applies a stated cap. Label the cap as fictional. The purpose is to show how an additional rule changes the relationship between company size and final weight, not to invent a current Nasdaq limit.
Keep rule assumptions beside the result. A percentage that looks precise can still be misleading if readers do not know which model produced it. A strong explanation makes the calculation reproducible and identifies which part would need authoritative information before being applied to the actual index.
How do component returns contribute to an aggregate?
In a simplified weighted-return exercise, multiply each component's return by its stated weight and combine the contributions. The real index calculation has its own definitions and treatment of events. Use the exercise to understand the relationship, not as a substitute for an official performance record.
Suppose invented weights are ten, twenty and seventy percent, with example returns of five, zero and minus one percent. The weighted contributions are plus 0.5, zero and minus 0.7 percentage points. The simplified aggregate is minus 0.2 percent, illustrating why a majority of favourable-looking individual observations does not automatically determine the total.
Ask students to explain the sign and units of every contribution. This prevents them from adding percentages without accounting for weights or confusing a percentage-point contribution with a component's own return. The labels are as important to understanding the result as the multiplication itself.
Is the Nasdaq-100 the same as a technology index?
The official scope includes non-financial companies across several industries. A popular shorthand should not replace that definition. Read current classifications and constituents if the question concerns sector exposure, rather than assuming that every company belongs to one narrowly defined technology category.
For a project, make an invented industry table and compare a company's sector label with its index membership. These are different classifications. A company can belong to a benchmark because it meets that benchmark's rules without the benchmark name becoming a complete description of all its business activity.
Avoid turning a broad market narrative into a statement about every member. A headline about one industry can be relevant context, but explaining the benchmark's actual movement requires appropriate information about the components, weights and period. The index definition alone does not establish the cause of a particular day's change.
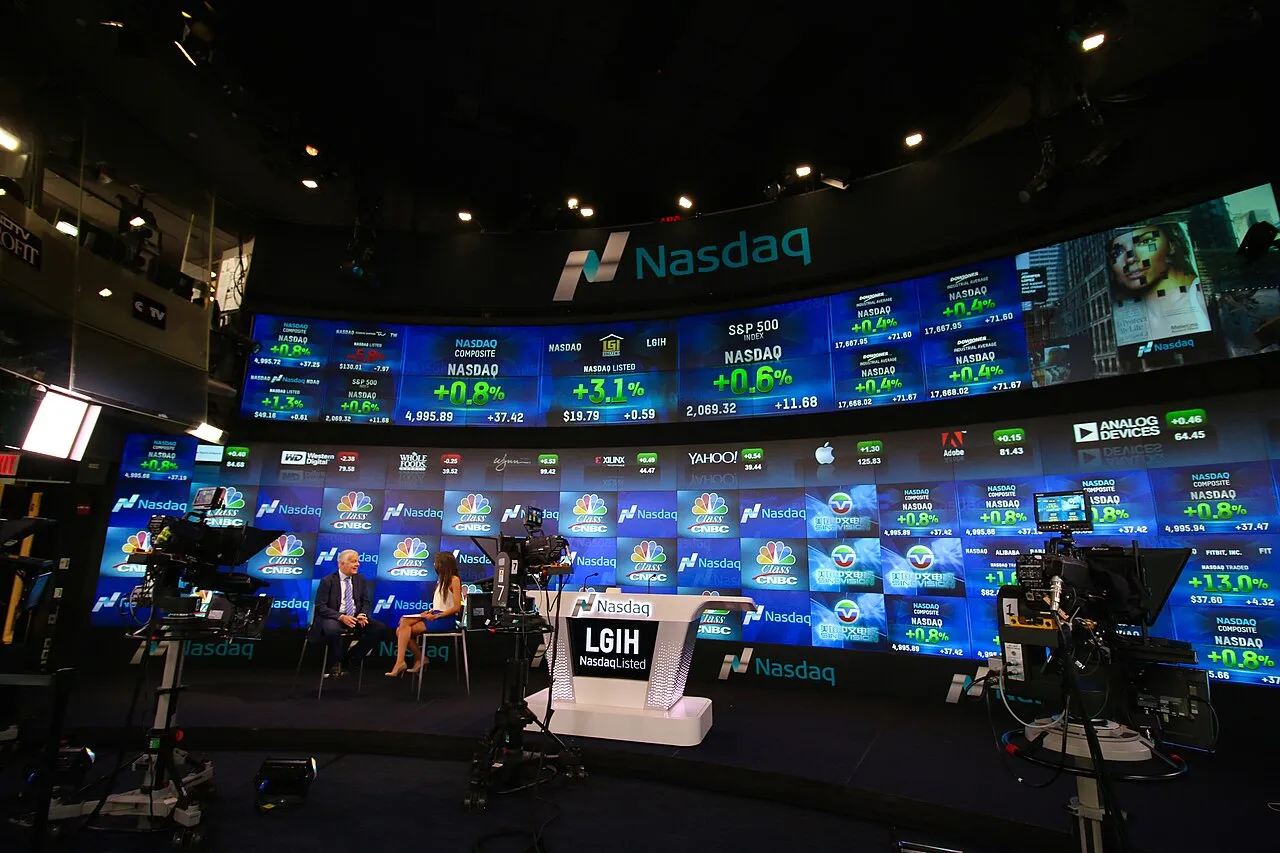
Nasdaq MarketSite photographed in 2015, shown as historical market context.
How should I read a quote or chart?
Identify the exact benchmark, timestamp, return version and reference period. A current-looking webpage can display delayed or historical information. A chart spanning several months and a headline describing one session are not interchangeable records even when they refer to the same index family.
Use an invented example rising from 10,000 to 10,200. The absolute movement is 200 points and the relative movement is two percent of the starting level. If a different reference is used, state it explicitly. The values are practice material, not a quote for any actual session.
Keep the date and time when sharing a screenshot. A saved image records what was shown at a particular moment; it is not a continuously updating feed. Clear labels make the observation useful later and help another reader reproduce the comparison without guessing which session was intended.
How do price and total-return versions differ?
Different return versions can treat distributions differently according to their rules. Read the version before comparing performance. A price movement and a reinvestment-based return do not necessarily answer the same question, even when both are described using the familiar name of an index.
For a toy example, separate a change in an asset's reference price from an invented distribution. Calculate each quantity under clearly stated assumptions. The exercise shows why the version label matters; it does not establish a real investor's return, tax treatment or the exact method used by a particular product.
When comparing two charts, align their periods, currencies and return definitions. Similar lines do not guarantee identical measurements. If a label is missing, identify the comparison as incomplete rather than assuming that the most familiar interpretation must be the one used by the source.
Are funds and futures identical to the index?
An index is a benchmark, while a linked fund or contract has its own structure and terms. A familiar benchmark name within a product title does not remove the need to read that product's documentation. Instrument type, costs, timing and other provisions can matter to the actual record being discussed.
For learning, compare the labels on an index overview and a product document without making a transaction. Identify the reference measure and the legal or operational product being described. The task is to understand the difference between a calculation and a financial instrument, not to select a strategy.
This guide does not assess suitability or explain how to use leverage. A technical understanding of weighting is not a substitute for the information needed for a personal financial decision. Keep the educational question narrow and use appropriate regulated information for matters outside its scope.
How does the Nasdaq-100 differ from the Dow or Sensex?
Start with scope and construction. Different benchmarks can represent different markets and use different weighting methods. Their point levels should not be compared as though a larger number automatically means that the underlying companies or economy are performing better.
The Dow Jones guide and Sensex guide explain related concepts. Retain each benchmark's own definition when using those comparisons. A shared word such as index does not establish identical constituents, currencies or methods.
Build a comparison table with market, scope, weighting and return version. Add the date of the official information used. This produces a more useful explanation than ranking the benchmarks by their displayed point values, which can be based on different scales and starting conventions.
What makes a useful student project?
Choose one question, such as how weights affect a simplified aggregate or why company and security counts can differ. Use a small invented dataset and write every assumption. A focused project demonstrates understanding more clearly than a long collection of current-looking screenshots without definitions.
Ask another learner to reproduce the calculation from the table alone. If they cannot identify the base or units, improve the labels. A small script can help check arithmetic, but it cannot decide whether an external source is current or whether two records use comparable definitions.
The programming courses provide available material for practising tables and calculations. Keep invented data visibly separate from official observations. The project should teach reasoning and source reading, not present a simulated result as an actual market performance record or a guaranteed future outcome.
What does rebasing a chart change?
Rebasing expresses different starting levels on a common reference scale. It can make relative movements easier to compare, but it does not alter the underlying observations or make different benchmarks identical. Read the chosen start date and return definition before interpreting the lines.
For an invented exercise, one level rises from 100 to 110 while another rises from 1,000 to 1,100. Both increase ten percent. Expressing both starting points as 100 makes that relative relationship easier to see. It does not establish that the original index point scales were directly comparable.
Explain why the chosen interval matters. Starting the chart on another date can change the comparison being made. A useful presentation states its reference point instead of selecting one that makes a preferred conclusion appear inevitable. Reproducible labels help readers evaluate the comparison rather than simply accepting its visual impression.
Frequently asked questions
Does Nasdaq always mean the Nasdaq-100?
No. Identify the exact exchange, benchmark or product being described. Similar names can refer to different records and scopes. The useful first step is to read the full label and source rather than assuming that every headline or search result uses the same definition.
Does a larger company always have an unrestricted weight?
Read the modified weighting rules in the current methodology. A simple capitalisation example explains a starting relationship but does not establish every adjustment or constraint in the actual index. Keep the example's assumptions separate from a statement about a real current weight.
Does this article provide a live forecast?
No. It explains methods and uses invented calculations. For current information, use the relevant official and market-data sources with their timestamps. A correct explanation of weighting does not determine the next market movement or establish that a financial product suits a particular reader.
Sources
Image credits: cover: ajay_suresh, source, CC BY 2.0. Resized and converted to WebP. inline: Luca Marfè at Italia all'ONU, source, CC BY 2.0. Resized and converted to WebP.
Found an error or an outdated detail? Report a correction with the article URL and original source.